Arable Market Report – 19 October 2026

Monday, 19 October 2026

This week's view of grain and oilseed markets, including a summary of both UK and global activity.

Grains

UK feed wheat futures, Nov-2026

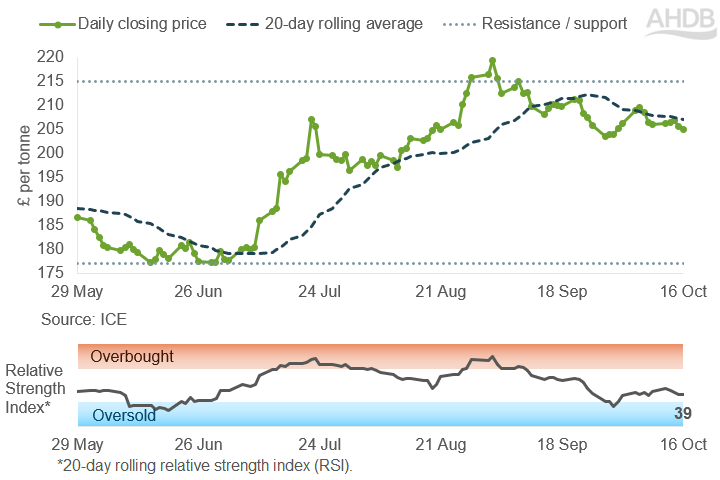
Figure 1. UK feed wheat futures prices, Nov-2026 contract, in £/tonne

A graph showing UK feed wheat futures price movement

Nov-2026 UK feed wheat futures ended last week at £205.00/t, £1.00/t lower than the previous Friday.

The solid line with markers shows the Nov-2026 prices in Figure 1.

The rise in Paris futures offered support to UK futures, as the UK-Paris relationship often impacts the attractiveness of imports into the UK.

However, a rise in sterling against the euro still led to the small week-on-week decline for UK futures. On Friday, the pound reached €1.1850, up from €1.1798 a week earlier and 16-month high.

The Relative Strength Index (RSI) declined from 42 on 9 October to 39 on 16 October, showing a easing in market momentum. This easing suggests the market could continue to drift, unless there’s new information to support prices.

Find out more about the graphs in this report and how to use them

Market drivers

While Chicago grain futures fell to their lowest levels since mid-August last week, European futures fared better. 

Potential export demand for European wheat supported Paris wheat futures. Higher crude oil prices, the war in Ukraine and a weak euro against the US dollar also factored.

Nearby Brent crude oil futures reached $109.86/barrel on Friday, its highest price since 19 May.

However, a reported uptick in Russian exports from September through the Baltic ports limited the price gains. 

Dec-2026 Paris wheat futures gained 0.7% Friday-Friday.

Algeria bought between 660 Kt and 720 Kt in a tender last week, according to trader reports. Reports indicate that the total could include some Romanian and/or Bulgarian wheat.

In contrast, a strong US dollar and better weather in the US for harvesting maize and planting winter wheat crop pushed Chicago prices lower. Selling by speculative traders added to the falls.

Dec-2026 Chicago maize futures fell 1.2% last week, with Dec-2026 Chicago wheat down 1.6%. 

This week, the conflicts in the Black Sea and Middle East and harvest reports are likely to influence prices.

Forecasts show drier weather again for key US maize areas. If confirmed, this could mean more harvest progress and pressure on prices.

Harvest is also underway in Australia. The Grain Industry Association of Western Australia increased its forecasts for wheat and barley output in the state after mild weather. But the forecasts remain 18% and 11% respectively below last year’s high levels. 

Rain has delayed the start of the wheat harvest in northern Argentina; the moisture could benefit developing barley crops. Low sunlight levels remain a watchpoint for all crops. 

The Buenos Aires Grain Exchange reports maize planting is well ahead of average, with over a third of the commercial area planted by 14 October.  

Table 1. Global grain futures prices

Futures market Contract month Price (per tonne) Change on week
UK feed wheat Nov-2026 £205.00 −£1.00
Paris milling wheat Dec-2026 €243.75 +€1.75
Chicago wheat Dec-2026 $242.67 −$3.86
Chicago maize Dec-2026 $186.71 −$2.17

UK delivered cereal prices

The price for bread wheat, delivered in Northants in November, was £224.50/t as at Thursday’s close. This was unchanged from the previous week's survey.
It also equated to a premium of £19/t over the Nov-2026 UK feed wheat futures contract. 

While the price itself is higher than that a year ago, the premium is lower. 

A year ago, the price for bread wheat, delivered in Northants in November 2025, was £187.50/t. But it equated to a £24.00/t premium to the Nov-2025 UK feed wheat futures contract.

Last week, the October price for feed wheat delivered in the West Midlands was £219.00/t. No direct week-on-week comparison is available.

Table 2. UK delivered cereal prices

Delivery specification Delivery month Price (per tonne) Change on week
N'hants bread wheat Nov-2026 £224.50 unchanged
E. Anglia feed wheat Nov-2026 n/a n/a
Yorkshire feed wheat Nov-2026 n/a n/a
E. Anglia feed barley Nov-2026 n/a n/a

n/a = not available

n/c = no comparison available.

Rapeseed

Paris rapeseed futures in £/t, May-2027

Figure 2. Paris rapeseed futures prices, May-2027 contract, £/tonne

A graph showing rapeseed futures price movement

May-2027 Paris rapeseed futures fell 0.9% in £/t last week to approx. £469/t.

The weekly fall was larger in £/t than in euro terms because of sterling strengthening against the euro.

The pound strengthened from € 1.1798 on 9 October to € 1.1850 on 16 October.

The May-2027 contract fell below the 20-day rolling average in the week and is now below the 50-day rolling average.

The solid line with markers in Figure 2 shows the May-2027 contract prices. The dashed line shows the 20-day rolling average, and the solid line shows the 50-day rolling average.

Market momentum is limited as prices have drifted and remain within recent ranges. The Relative Strength Index (RSI) was at 44 on Friday, down from 50 last week, moving closer to oversold.

Find out more about the graphs in this report and how to use them

Market drivers

Oilseed markets continue to remain volatile, but broadly pressured across the week. Sustained high crude oil prices, currency and US harvest progress were the main drivers across the week.  

Over the last week, May-2027 Paris rapeseed futures fell 0.5%. May-2027 Winnipeg canola futures fell 1.9% and May-2027 Chicago soyabeans dropped 2.6%.

Over the past seven days, dry weather across the main US soyabean-producing states has supported harvest progress, which has fed into downward price pressure. The latest USDA crop progress report, out this evening (22:00 BST), should give further insights. Further to that, with little rainfall forecast over the US Midwest in the coming week, harvest is likely to keep advancing quickly, which could keep prices under pressure.

Despite the oilseed market unwinding the US weather risk premium, demand remains strong. In the latest US export sales data (week ending 08 Oct), US soyabean export sales reached 574.9 Kt, up 5% on the week, with China accounting for 126.8 Kt. However, total sales came in at the low end of trade estimates.

Nearby Brent crude futures traded broadly sideways for most of last week, then rose 3.7% on Friday to close at $109.86/barrel. The rise was driven by escalating Middle East tensions and doubts over Russian diesel supply. If these supply risks persist, Friday's gains could carry upward pressure into this week's opening. Brent crude prices likely adding price support to a well-supplied oilseed market.

The Grain Industry Association of Western Australia (GIWA) cut its Western Australian canola forecast by 179.5 Kt to 4.6 Mt as harvest gets underway. Output is still expected to be 5% above last year's 4.37 Mt.

An intense El Niño-driven drought has disrupted palm oil supply in Indonesia. Low water on West Kalimantan's main river has halted shipments and forced mills to cut purchases, and national production forecasts have been revised down (LSEG), looking ahead this El Niño event could have on-going impacts going into 2027 for palm oil.

Table 3. Global oilseed and oil futures prices

Futures market Contract month Price (per tonne) Change on week
Paris rapeseed May-2027 €556.25 −€3.00
Chicago soyabeans May-2027 $474.77 −$12.77
Chicago soyabean oil May-2027 $1,492.96 −$21.38
Brent crude oil nearby $109.86 +$5.14

*Brent crude oil price per barrel

UK delivered rapeseed prices

The delivered price for rapeseed into Erith in November was £468.00/t in Friday’s survey. The delivered price for Liverpool in November was also £468.00/t. 

The delivered price into East Anglia in November was £466.50/t.
All locations were £5.50/t lower than those in the previous survey on Friday 9 October.

Erith and Liverpool prices for February delivery saw downward price pressure, down £6.50/t, to £475.00/t. East Anglia prices for February also saw downward price pressure, falling £6.50/t to £473.50/t.

The delivered price for harvest 2027 was down £5.00/t on the week to £455.50/t for both Erith and Liverpool. Delivered price for harvest 2027 into East Anglia was quoted at £454.50/t, with no comparison on the week.

Table 4. UK delivered rapeseed prices

Delivery specification Delivery month Price (per tonne) Change on week
Erith Nov-2026 £468.00 −£5.50
Liverpool Nov-2026 £468.00 −£5.50
East Anglia Nov-2026 £466.50 −£5.50

Extra information

Trade data

HMRC released UK trade data for August 2026 on 15 October. UK wheat imports totalled 148 Kt in August, bringing imports in the first two months of the 2026/27 season (July and August) to 343 Kt. This is 108 Kt lower than the 450 Kt imported during the same period last season.

UK maize imports reached 266 Kt in August, up from 216 Kt in July. Combined July and August imports totalled 482 Kt, compared with 263 Kt over the same period in 2025/26. Higher maize imports may reflect maize pricing competitively for animal feed relative to wheat.

AHDB Cereals & Oilseeds Balance Sheet

AHDB will publish its first supply and demand estimates for the 2026/27 season on Thursday 22 October. This will provide an early balance sheet for UK wheat and barley, including estimates of production, imports and demand for the new crop year.

Northern Ireland

Table 5. Delivered prices into Belfast*

Delivery specification** Delivery month Price (per tonne) Change on week
Feed barley  - spot Spot £216.00 n/c
Feed barley  - forward Nov-26 £223.50 n/c
Feed wheat  - spot Spot n/a n/a
Feed wheat  - forward Nov-26 £240.00 n/c

*Prices provided for indicative purposes

**Basis is imported/home-grown

n/c = no comparison available


Sign up to receive the latest information from AHDB

While AHDB seeks to ensure that the information contained on this webpage is accurate at the time of publication, no warranty is given in respect of the information and data provided. You are responsible for how you use the information. To the maximum extent permitted by law, AHDB accepts no liability for loss, damage or injury howsoever caused or suffered (including that caused by negligence) directly or indirectly in relation to the information or data provided in this publication.

All intellectual property rights in the information and data on this webpage belong to or are licensed by AHDB. You are authorised to use such information for your internal business purposes only and you must not provide this information to any other third parties, including further publication of the information, or for commercial gain in any way whatsoever without the prior written permission of AHDB for each third party disclosure, publication or commercial arrangement. For more information, please see our Terms of Use and Privacy Notice or contact the Director of Corporate Affairs at info@ahdb.org.uk  © Agriculture and Horticulture Development Board. All rights reserved. 

×