EU beef supplies continue to tighten: Beef market update

Wednesday, 23 September 2026

EU beef supplies tightened during the first half of 2026. Can higher imports and lower exports offset falling domestic output, or will reduced availability continue to support cattle prices and reshape the market?

Key points

  • EU beef production for the year to date (Jan-Jun), decreased by 2% year-on-year to 3.8 million tonnes (Mt) reflecting herd contraction, environmental regulation and profitability pressures.
  • EU imports of fresh/frozen beef for the year to date (January – July) increased by 9% (15,500t) year-on-year to 188,700
  • EU exports of fresh/frozen beef increased by 2% year-on-year (6,100t) to 262,600t
Image of staff member Hannah McLoughlin

Hannah McLoughlin

Trainee Analyst

See full bio

Production

According to data from the European Commission, EU beef production for the year to date (Jan-Jun), decreased by 2% year-on-year to 3.8 million tonnes (Mt).

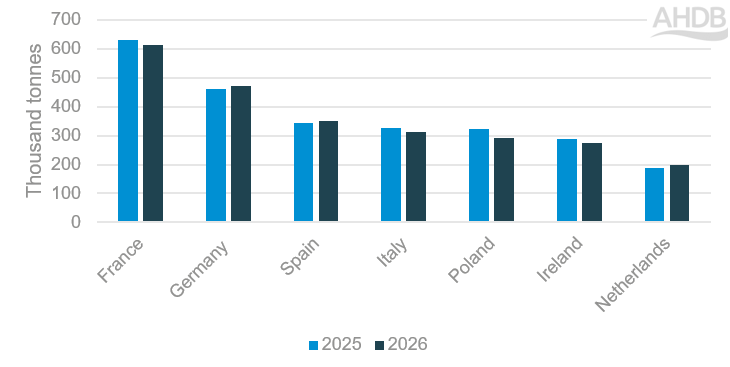
Figure 1. Beef production of select EU27 countries for YTD (Jan-Jun)


  a bar chart comparing year-to-date (January to June) beef production in selected EU27 countries for

 Source: European Commission

Figure 1 shows a bar chart comparing year-to-date (January to June) beef production in selected EU27 countries for 2025 and 2026, measured in thousand tonnes.

Poland saw the largest decrease of 10% (32,000t) to 292,000 tonnes. Ireland (-6%) and Italy (-4%) also saw declines.

The Netherlands was one of the few countries to record an increase in beef production during the first half of 2026, with an increase of 6% (11,000 t) to 200,000 tonnes. Germany saw a marginally increase of 2% (8,000t) to reach 471,000 tonnes. Spain also saw an increase of 1% to 350,000 tonnes.

Looking at the different categories of beef production cow production fell to 900,000t, a decrease of 2%. Ireland saw a significant (15%) decrease. Prime beef production decreased by approximately 1%, to reach an estimated 1.8Mt, this was primarily driven by lower heifer production.

Prices

GB steer prices saw a gradual decline in the start of 2026 before a sharper fall in May and June. Continental prices have undergone a sharper adjustment, narrowing the competitiveness gap between the GB price.

Irish prices have softened considerably, likely reflecting increased cattle availability.

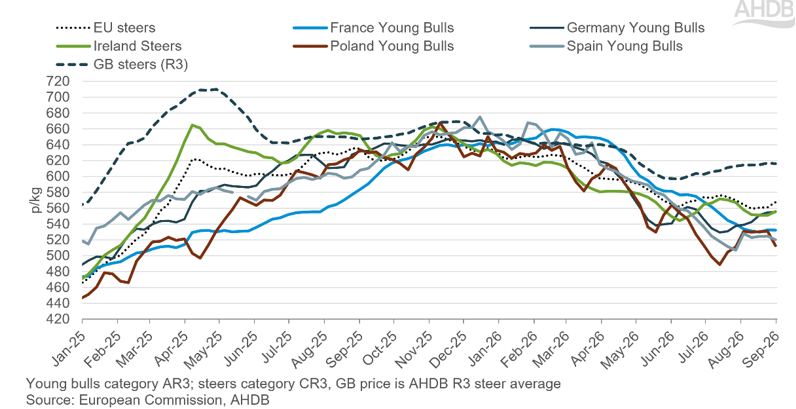
Figure 2. Selected EU deadweight prime cattle prices (p/kg)

  a line chart showing selected EU deadweight prime cattle prices (pence per kilogram) from January 20

Figure 2 shows a line chart showing selected EU deadweight prime cattle prices (pence per kilogram) from January 2025 to September 2026.

France has experienced one of the steeper corrections among major EU producers, erasing much of the premium built throughout late 2025.

Spain has recorded one of the largest declines in the group, moving from the highest-priced market early in the year to among the lowest by late summer.

Poland has seen large levels of volatility due to the structure of the Polish beef sector and its reliance on exports.

Tighter beef supply overall is helping to support prices across the bloc.

Trade

Total EU imports of fresh/frozen beef for the year to date (January – July) increased by 9% (15,500t) year-on-year to 188,700.

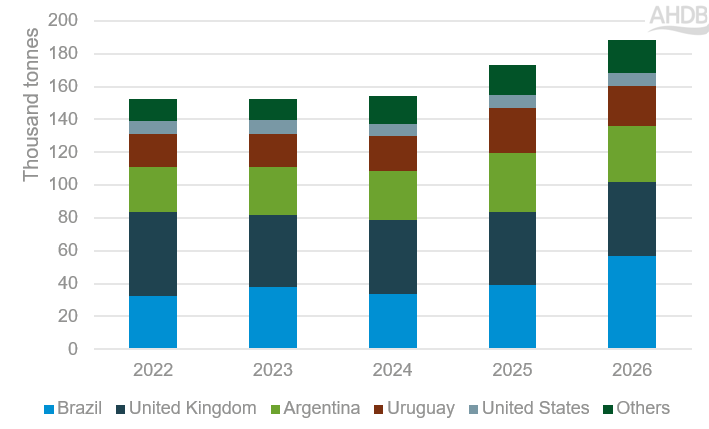
Brazil has overtaken the UK as the top supplier in terms of volume, shipping 56,500t across the period (+44% year-on-year). Brazilian beef exports to the EU surged ahead of the 3 September ban, with traders eager to secure supply.

Imports from Argentina (-1,600t) and Uruguay (-2,800t) decreased potentially due to trade flows being redirected towards Brazil.

Figure 4. EU27 beef import volumes by supplier country YTD Jan-Jun for 2022-2026

  a bar chart showing EU beef imports by origin from 2022 to 2026, with total imports increasing over

Source: Eurostat compiled by Trade Data Monitor LLC

Figure 4 shows a bar chart showing EU beef imports by origin from 2022 to 2026, with total imports increasing over the period.

For the same period, EU exports of fresh/frozen beef increased by 2% year-on-year (6,100t) to 262,600t.

Exports to the UK decreased by 11% (13,200t) to 108,400t.

Exports to Norway increased by 232% (10,000t) to 14,000t, reflecting Norway's continued reliance on imported beef to supplement domestic production. Coupled with exports to Turkey increasing 50% (17,500t) to 52,600t.

The growth could suggest that EU exporters have targeted nearby premium markets with strong import demand, as high EU prices and tighter supplies reduced competitiveness in some traditional export destinations.

Market balance

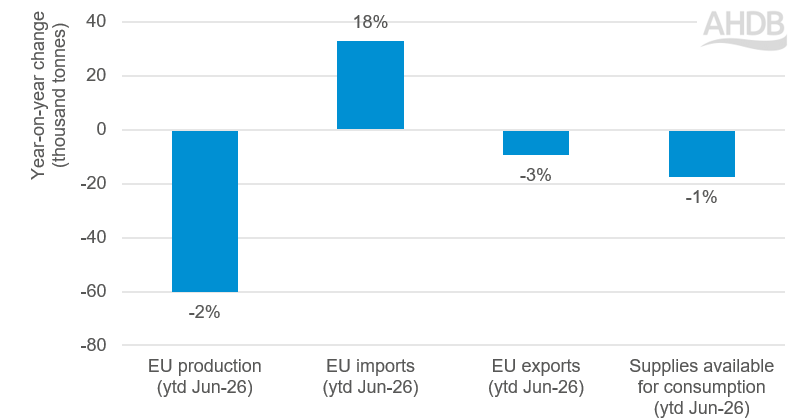
The latest EU beef market balance highlights the growing pressure on domestic production. This decline was the most significant change across the supply balance and reflects continued structural challenges facing the sector, including herd contraction, environmental regulations and profitability pressures in several key producing countries.

Figure 3. EU beef market balance YTD Jan-Jun

a bar chart showing year-on-year changes in EU beef supply components (YTD January to June 2026, tho

Source: European Commission, Trade Data Monitor LLC, Eurostat

Figures are in carcase weight equivalent and are for Jan-Jun rather than Jan-July so may not match figures quoted elsewhere.

Figure 3 shows a bar chart showing year-on-year changes in EU beef supply components (YTD January to June 2026, thousand tonnes).

To help offset lower domestic production, EU beef imports increased by approximately 33 thousand tonnes, representing an 18% year-on-year rise (in carcase weight equivalent). At the same time, exports declined. However, these adjustments were insufficient to fully compensate for the reduction in production.

As a result, supplies available for consumption fell by around 18 thousand tonnes, equivalent to a 1% decline year-on-year. If domestic output continues to decline, greater dependence on imports may be required, potentially exposing the market to increased competition for imported product and supporting firmer beef prices across the region.

Market reports suggest extreme summer temperatures weighed on beef demand in some EU key producing countries notably France, particularly for minced beef. In response to slower market activity and the holiday season, some abattoirs scaled back operations. Despite weaker overall demand, well-finished animals continued to attract buyer interest.

What does this mean for the UK beef market?

For the UK, tightening EU beef supplies could provide continued support for cattle prices and export opportunities. With production declining across much of Europe, the EU is becoming increasingly reliant on imports to balance demand.

Recent restrictions on Brazilian beef could further tighten availability and create opportunities for alternative suppliers, including the UK. However, the scale of the impact remains uncertain. There is a question as to where this product will end up, with a potential risk of it coming to the UK, this is a watch point going forward. Overall market conditions are expected to remain supportive, helping to underpin UK beef prices and export demand.


Sign up for regular updates

You can subscribe to receive Beef and Lamb market news straight to your inbox. Simply fill in your contact details on our online form.

Visit the Keep in touch page

While AHDB seeks to ensure that the information contained on this webpage is accurate at the time of publication, no warranty is given in respect of the information and data provided. You are responsible for how you use the information. To the maximum extent permitted by law, AHDB accepts no liability for loss, damage or injury howsoever caused or suffered (including that caused by negligence) directly or indirectly in relation to the information or data provided in this publication.

All intellectual property rights in the information and data on this webpage belong to or are licensed by AHDB. You are authorised to use such information for your internal business purposes only and you must not provide this information to any other third parties, including further publication of the information, or for commercial gain in any way whatsoever without the prior written permission of AHDB for each third party disclosure, publication or commercial arrangement. For more information, please see our Terms of Use and Privacy Notice or contact the Director of Corporate Affairs at info@ahdb.org.uk  © Agriculture and Horticulture Development Board. All rights reserved. 

×